Our mission is to help computational modelers develop, document, and share their computational models in accordance with community standards and good open science and software engineering practices. Model authors can publish their model source code in the Computational Model Library with narrative documentation as well as metadata that supports open science and emerging norms that facilitate software citation, computational reproducibility / frictionless reuse, and interoperability. Model authors can also request private peer review of their computational models. Models that pass peer review receive a DOI once published.
All users of models published in the library must cite model authors when they use and benefit from their code.
Please check out our model publishing tutorial and feel free to contact us if you have any questions or concerns about publishing your model(s) in the Computational Model Library.
Displaying 10 of 254 results for "Marcel Volosin" clear search
HousingABM_Japan: An Agent-Based Model of Price and Rent Amplification in the Tokyo Housing Market
Eiki Tamama | Published Sunday, September 06, 2026HousingABM_Japan is a NetLogo agent-based model of the residential market of Tokyo’s 23 wards. It evaluates whether a single parameter configuration can jointly reproduce key features of prices, rents, yields, and market turnover across distinct market regimes from 2001 to 2025, with particular attention to demand- and supply-side trend-following during the 2021–2025 price surge.
The model builds on the Bank of England housing-market lineage (Baptista et al. 2016; Carro et al. 2023) and introduces four extensions: (1) dynamic linkages between the sale and rental markets through vacancy, rents, and yields; (2) heterogeneous demand-side trend-following; (3) supply-side trend-following through construction-cost trend anchoring and a momentum-dependent dynamic premium; and (4) housing-equity borrowing that converts unrealized equity into additional borrowing capacity.
Twenty parameters are calibrated using 2001–2015 data and held fixed for post-calibration evaluation over 2016–2020 and 2021–2025, while annual exogenous inputs follow observed historical paths. The model reproduces the shift from moderate price growth to the 2021–2025 surge, as well as rent acceleration, surge-period yield compression, and persistently low market turnover, although it understates the intermediate acceleration of 2016–2020.
…
Market-level effects of firm-level adaptation and intermediation in networked markets of fresh foods: a case study in Colombia.
César García-Díaz | Published Sunday, April 12, 2020 | Last modified Sunday, April 12, 2020This a model developed as a part of the paper Mejía, G. & García-Díaz, C. (2018). Market-level effects of firm-level adaptation and intermediation in networked markets of fresh foods: a case study in Colombia. Agricultural Systems 160: 132-142.
It simulates the competition dynamics of the potato market in Bogotá, Colombia. The model explores the economic impact of intermediary actors on the potato supply chain.
A Double-Auction Equity Market For a Single Firm with AR1 Earnings
Eric Weisbrod | Published Monday, December 13, 2010 | Last modified Saturday, April 27, 2013This is a final project for the class AML 591 at Arizona State University. I have done a small amount of bug-checking, but overall the project represents only a half of a semester’s work, so proceed w
SERDUX-MARCIM: agent-based simulation of cyberattack propagation in maritime critical infrastructure
Diego Edison Cabuya Padilla Carlos A Castaneda-Marroquin Daniel Díaz-López | Published Thursday, August 20, 2026 | Last modified Tuesday, October 20, 2026SERDUX-MARCIM simulates the propagation of a cyberattack over the computational network of an organization in the maritime sector, at the strategic level of decision-making. It is the instantiation of ABM-MARCIM, the agent-based model of the MARCIM framework for the modeling and simulation of maritime cyberdefense.
Every computational asset of the target organization – servers, endpoints, routers, gateways, vessel systems, radars – is an agent that occupies one of six states at each time step: Susceptible, Exposed, Resistant, Degraded, Unavailable or Destroyed, the initials of which give the model its name. The states Degraded, Unavailable and Destroyed are associated with the D5 cyberattack effects (disrupt, degrade, deny, destroy, deceive) as a function of the degree and the duration of the attack. Thirteen transitions between states are admissible.
Unlike a conventional agent-based model, the local update function is not an individual behavioral rule. It is a system of six ordinary differential equations with eight time-dependent transition rates – propagation, cyberattack (degraded), cyberattack (unavailable), cyberattack (destroyed), recovery, sanitation, loss of resistance, and unavailability by other causes. The values of those rates derive from the capabilities of the target organization, the capabilities of the attacker, and the degree and duration of the cyberattack, computed through a cyber risk approach aligned with the OWASP Risk Rating Methodology, the ISACA categorization of security controls and the IMO Guidelines on Maritime Cyber Risk Management.
…
Cellular automata model of social networks
Rubens de Almeida Zimbres | Published Tuesday, August 02, 2022This project was developed during the Santa Fe course Introduction to Agent-Based Modeling 2022. The origin is a Cellular Automata (CA) model to simulate human interactions that happen in the real world, from Rubens and Oliveira (2009). These authors used a market research with real people in two different times: one at time zero and the second at time zero plus 4 months (longitudinal market research). They developed an agent-based model whose initial condition was inherited from the results of the first market research response values and evolve it to simulate human interactions with Agent-Based Modeling that led to the values of the second market research, without explicitly imposing rules. Then, compared results of the model with the second market research. The model reached 73.80% accuracy.
In the same way, this project is an Exploratory ABM project that models individuals in a closed society whose behavior depends upon the result of interaction with two neighbors within a radius of interaction, one on the relative “right” and other one on the relative “left”. According to the states (colors) of neighbors, a given cellular automata rule is applied, according to the value set in Chooser. Five states were used here and are defined as levels of quality perception, where red (states 0 and 1) means unhappy, state 3 is neutral and green (states 3 and 4) means happy.
There is also a message passing algorithm in the social network, to analyze the flow and spread of information among nodes. Both the cellular automaton and the message passing algorithms were developed using the Python extension. The model also uses extensions csv and arduino.
This agent-based model (ABM), developed in NetLogo and available on the COMSES repository, simulates a stylized, competitive electricity market to explore the effects of carbon pricing policies under conditions of technological innovation. Unlike traditional models that treat innovation as exogenous, this ABM incorporates endogenous innovation dynamics, allowing clean technology costs to evolve based on cumulative deployment (Wright’s Law) or time (Moore’s Law). Electricity generation companies act as agents, making investment decisions across coal, gas, wind, and solar PV technologies based on expected returns and market conditions. The model evaluates three policy scenarios—No Policy, Emissions Trading System (ETS), and Carbon Tax—within a merit-order market framework. It is partially empirically grounded, using real-world data for technology costs and emissions caps. By capturing emergent system behavior, this model offers a flexible and transparent tool for analyzing the transition to low-carbon electricity systems.
LaMEStModel
Ruth Meyer | Published Friday, October 12, 2018The Labour Markets and Ethnic Segmentation (LaMESt) Model is a model of a simplified labour market, where only jobs of the lowest skill level are considered. Immigrants of two different ethnicities (“Latino”, “Asian”) compete with a majority (“White”) and minority (“Black”) native population for these jobs. The model’s purpose is to investigate the effect of ethnically homogeneous social networks on the emergence of ethnic segmentation in such a labour market. It is inspired by Waldinger & Lichter’s study of immigration and the social organisation of labour in 1990’s Los Angeles.
Dynamic pricing strategies for perishable products in a competitive multi-agent retailer market
Wenchong Chen Hongwei Liu | Published Monday, November 27, 2017 | Last modified Thursday, March 01, 2018This model explores a price Q-learning mechanism for perishable products that considers uncertain demand and customer preferences in a competitive multi-agent retailer market (a model-free environment).
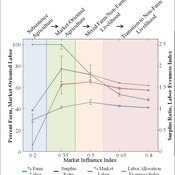
Land-Livelihood Transitions
Nicholas Magliocca Daniel G Brown Erle C Ellis | Published Monday, September 09, 2013 | Last modified Friday, September 13, 2013Implemented as a virtual laboratory, this model explores transitions in land-use and livelihood decisions that emerge from changing local and global conditions.
An Agent-Based Model of an Insurance Market driven by Supply and Demand with Imperfectly Estimated Strategies in C#
Rei England | Published Sunday, September 24, 2023This is a simulation of an insurance market where the premium moves according to the balance between supply and demand. In this model, insurers set their supply with the aim of maximising their expected utility gain while operating under imperfect information about both customer demand and underlying risk distributions.
There are seven types of insurer strategies. One type follows a rational strategy within the bounds of imperfect information. The other six types also seek to maximise their utility gain, but base their market expectations on a chartist strategy. Under this strategy, market premium is extrapolated from trends based on past insurance prices. This is subdivided according to whether the insurer is trend following or a contrarian (counter-trend), and further depending on whether the trend is estimated from short-term, medium-term, or long-term data.
Customers are modelled as a whole and allocated between insurers according to available supply. Customer demand is calculated according to a logit choice model based on the expected utility gain of purchasing insurance for an average customer versus the expected utility gain of non-purchase.
Displaying 10 of 254 results for "Marcel Volosin" clear search